Paris Jackson is asking a Los Angeles court to reduce the management fee paid for running her father’s estate, opening a new chapter in a disagreement over compensation and financial reporting. Her request centers on a substantial figure: $109.2 million in combined compensation submitted for approval for 2023 and 2024.
That amount covers co-executors John Branca and the late John McClain, along with legal compensation. Paris argues that the estate’s financial accountings do not adequately support the request. She wants the management rate reduced from 15% to 10% of gross entertainment-related income. The estate disputes her allegations. Its representatives say the management arrangement was authorized by the court, that the executors waived statutory executor compensation, and that financial accountings Paris is challenging have already been filed.
Paris is one of several family members who benefit from the estate, alongside her brothers Prince Jackson and Bigi Jackson, and their grandmother, Katherine Jackson. The disagreement centers on two questions with significant consequences for that financial legacy: how much the professionals operating Michael Jackson’s business should earn, and what financial information should accompany approval of their compensation.
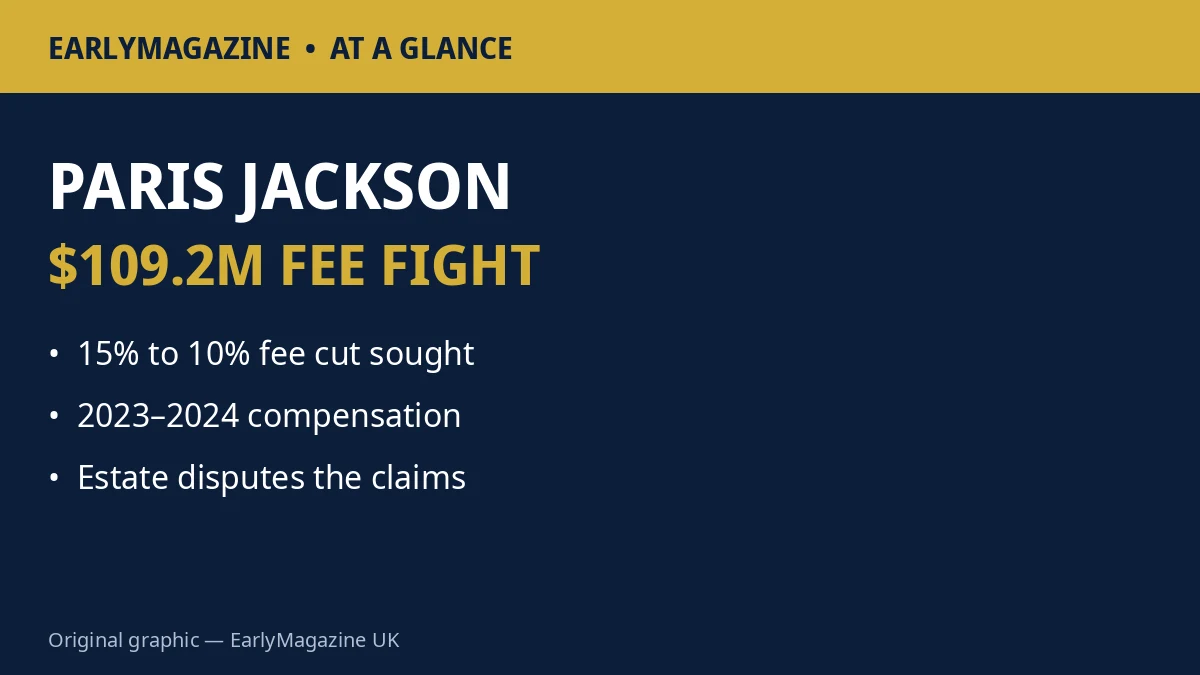
Paris Jackson Estate Fee Fight at a Glance
| Compensation at issue | $109,219,648 for 2023 and 2024 (executors + legal, combined) |
| Fee rate Paris wants changed | From 15% to 10% of gross entertainment-related income |
| Effect of the cut | A one-third reduction in the fee on the same income base |
| Paris’s allegation | 2023 and 2024 accountings incomplete; Sept 15 disclosure deadline missed |
| Estate’s position | Arrangement court-authorized; accountings filed; later deadlines not yet due |
What the $109 Million Represents
According to Rolling Stone’s reporting on Paris’s October 23 motion, the compensation at issue totals $109,219,648 for the two-year period. It is an aggregate covering the co-executors and lawyers, rather than an individual payment to Branca. McClain, who helped manage the estate alongside Branca from 2009, died in May 2026.
Paris’s objection concerns the supporting financial records. She alleges that the 2023 and 2024 accountings were incomplete and that a September 15 deadline for complete disclosures was missed. Her position is that the court needs adequate information to evaluate compensation of this size. The estate maintains that those accountings have been submitted. The disagreement therefore includes the adequacy of the filings, as well as the compensation itself.
The Management Fee Paris Wants Changed
Paris is seeking a five-percentage-point reduction in the management rate, from 15% to 10%. That would amount to a one-third reduction in the fee on the same income base. For a simple illustration, assume the estate receives $100 million in income covered by the arrangement. A 15% fee would be $15 million; a 10% fee would be $10 million. The difference would leave another $5 million in the estate before other expenses and distributions.
The proposed reduction would apply to 2023, 2024, and subsequent years until a complete 2026 accounting is filed. Her request ties the lower rate to the delivery of the financial information she is seeking. The $109.2 million compensation total includes multiple recipients and categories of payment. Calculating the dollar effect of a rate change would require identifying the income and compensation covered by the court’s eventual decision.
The Estate’s Response
The estate’s response emphasizes the distinction between administering a deceased person’s estate and operating the commercial business that continues to generate income from that person’s work. Its representatives say Branca and McClain waived the statutory compensation available to executors and instead received a separate management fee approved by the court.
In a statement to TMZ, an estate representative described that payment as “a separate, court-ordered management fee for operating the hugely successful Michael Jackson business.” The estate also disputes the premise of the requested accounting penalties. Its representative says the 2023 and 2024 accountings have been filed and that the deadlines for the 2025 and 2026 accountings have not yet arrived.
Percentage-based compensation has been part of the estate’s management structure for years. In 2010, a judge approved an arrangement giving Branca and McClain a combined 10% of specified entertainment-related income, with major exclusions. The court subsequently approved changes involving professional services, including legal work by Branca’s firm. Those earlier arrangements show that compensation has evolved under court oversight as the business has expanded.
The Business Behind the Fees
When Michael Jackson died in 2009, he left valuable music rights alongside hundreds of millions of dollars in debt and a complicated collection of business obligations. Branca and McClain oversaw a turnaround that generated revenue through music, licensing, theatrical productions, and major transactions.
In 2016, Sony acquired the estate’s remaining 50% interest in Sony/ATV Music Publishing in a transaction involving $750 million in total payments. The company included the Beatles publishing rights Jackson had acquired decades earlier. In 2024, Sony acquired a 50% interest in a package of Jackson’s recorded-music and publishing assets in a deal reported at at least $600 million. That transaction included Mijac publishing assets. Alongside these transactions, the estate developed projects including “This Is It,” Cirque du Soleil productions, and “MJ the Musical,” while continuing to earn income from recordings and licensing.
Managing that business involves negotiating deals, developing productions, protecting intellectual property, and handling legal and financial matters. The estate points to its commercial results in defending its compensation structure. Paris’s motion asks the court to assess the reporting obligations that accompany that structure.
The Earlier $625,000 Bonus Dispute
The latest motion follows a separate disagreement over $625,000 in bonuses paid to outside law firms for work in 2018. Before a judge ordered the payments returned to the estate, the court found that the information presented did not sufficiently justify those particular bonuses. The payments had gone to outside counsel, and the estate’s representatives said the firms had agreed to return funds if the court declined to approve them.
The same ruling also acknowledged the management team’s achievements. In a statement reported by ABC News, the estate’s attorneys highlighted the court’s recognition of the estate’s financial transformation and the creation of “real and substantial generational wealth” for its beneficiaries. The estate said it disagreed with the bonus decision but respected it.
That history gives the current dispute useful context. The management team’s commercial accomplishments and Paris’s requests for financial disclosure are both part of the record. The new motion asks the court to decide whether the accounting issues she alleges warrant changing the fee arrangement; the estate maintains that its filings and court-approved compensation do not justify that reduction. No decision on the new motion has been reported yet.
For more on the Jackson legacy and celebrity fortunes, see our Michael Jackson profile, Taylor Swift net worth and Dua Lipa net worth profiles.
